Walk into an Indian middle-class home in Mumbai or Bengaluru, and you’ll likely find a mop, a broom, and perhaps a ceiling fan that doubles as a dust distributor. The vacuum cleaner? It’s still a guest that hasn’t been invited to stay. Household penetration sits below 1%—0.89% to be precise, according to Redseer data from FY25 [citation:9]. That number is either a warning sign or the biggest opportunity in the small appliance sector. For cordless stick vacuum brands, it’s both.
The instinct for any manufacturer eyeing India is to slash prices. Get under ₹10,000, get under ₹8,000, and watch the volumes explode. But the data tells a messier story. India’s vacuum market grew 10% in retail volume in 2025, reaching 1.3 million units, yet the top two brands—Eureka Forbes and Agaro—control 71% of that volume [citation:1][citation:7]. The market is concentrated, the consumer is cautious, and the “cheap vacuum” strategy alone isn’t converting broom-wielding households. Something else is happening.
The Price Paradox: Cheap Doesn’t Always Mean Convincing
India is undeniably price-sensitive. Industry executives openly acknowledge that successive price hikes in consumer durables have suppressed volume growth in entry-level segments, even during the festive season when discounts are supposed to drive purchases [citation:12]. But vacuum cleaners occupy a strange psychological space. Unlike a television or an air conditioner, a vacuum is not yet a “necessary” appliance for most Indian households. It’s a considered purchase—one that requires the buyer to believe the product will actually work in their specific home environment.
That skepticism is earned. Indian homes are dustier, floors are often harder (marble, tile, granite), and the idea of replacing a daily jhadu with a battery-powered stick is not a trivial cultural shift. When a consumer spends ₹8,000 on a cordless vacuum and finds it choking on fine dust or running out of charge mid-cleaning, the experiment fails—and that failure gets shared with the extended family, the WhatsApp group, the neighbor. In a market this small, bad word-of-mouth travels faster than any ad campaign.
IndexBox’s analysis of the India wet-dry vacuum market identifies the sweet spot clearly: companies that target the **INR 5,000–8,000 cordless price point** with reliable battery performance, strong suction, and visible warranty support will unlock the largest volume tier [citation:4]. The emphasis is not on the price alone. It’s on the three pillars that make a low-price product trustworthy: battery, suction, warranty. Miss any one, and the consumer returns to the broom.
What Indian Consumers Actually Do With a Vacuum
Here’s where the global playbook fails. In mature markets, a cordless stick vacuum is often a secondary cleaning tool—a quick-clean device for crumbs and pet hair between deeper cleans. In India, for the households that do buy one, it frequently becomes the primary cleaning tool. That changes the engineering requirements entirely.
Dreame’s India managing director put it bluntly in an interview: “In India, without mopping, the house is not clean” [citation:6]. A dry-only cordless stick vacuum that works beautifully on a German hardwood floor may feel incomplete on an Indian tile floor where the expectation is a wet wipe-down afterward. This is why wet-and-dry functionality, or at least a mopping attachment, has become a quiet battleground in the mid-range segment.
The usage patterns also skew heavily toward urban, nuclear, and working-couple households in the top 20 cities, with South India accounting for a disproportionate share of demand—nearly 45% of the robot vacuum category, a figure that likely reflects similar dynamics in the stick segment [citation:6]. The driver isn’t gadget enthusiasm. It’s the difficulty of finding reliable domestic help and the time pressure of dual-income households. A cordless vacuum isn’t a luxury in these homes. It’s a logistics solution.
The China Factor and the Localization Imperative
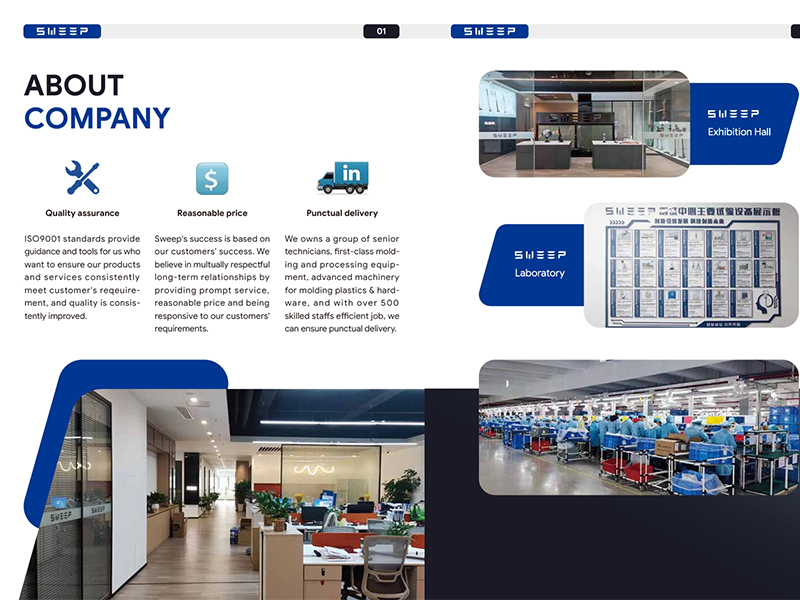
Chinese manufacturers dominate the global supply of cordless vacuums, and India’s import data reflects that reality. Roughly 40–50% of India’s wet-dry vacuum market by value is met by imports of finished goods, primarily from China and Vietnam [citation:4]. For a **cordless stick vacuum China**-sourced product, the landed cost advantage is real. But the brands that are gaining traction in India are not simply shipping Chinese SKUs with a new label.
The localization that matters is not just about voltage or plug type. It’s about service infrastructure. More than 17% of Indian vacuum owners report dissatisfaction with after-sales support, and over 32% are neutral—meaning they haven’t been impressed enough to become advocates [citation:5]. In a market where the product is unfamiliar and the price is a stretch, a broken vacuum with no clear repair path becomes a cautionary tale that suppresses the entire category.
Brands that are serious about India are building service networks city by city. Dreame, for instance, offers home service and pick-up/drop-off in 165 cities, with plans to expand to 200 [citation:6]. That kind of infrastructure doesn’t show up in the product spec sheet, but it shows up in conversion rates. When a consumer at a retail counter asks “what if it stops working,” a credible answer matters more than a five-minute runtime advantage.
The ₹5,000 Question
The most aggressive price point under discussion is ₹5,000. At that level, a cordless vacuum becomes an impulse-adjacent purchase for urban middle-class households—less than a mid-range smartphone, comparable to a decent mixer grinder. But building a product that survives Indian conditions at that price is genuinely difficult. Lithium-ion cell costs, motor quality, and filtration all compete for the same bill of materials.
This is where the supply chain expertise of Chinese OEMs becomes critical. The brands that can source from established **cordless stick vacuum China** manufacturers with proven quality control—rather than chasing the absolute lowest quotation—are the ones positioned to hold the ₹5,000–8,000 line without bleeding returns. The temptation to strip features to hit a price tag is strong. The smarter play is to strip the *right* features: keep the suction, keep the battery reliability, keep the warranty, and simplify the accessories. An Indian consumer who gets one brush that works well on tile and one extra filter is happier than one who gets five attachments and a vacuum that dies in eight months.
What the Robots Teach Us
An interesting signal comes from the robot vacuum segment. Despite higher prices, robot vacuums are now the most common vacuum format among Indian owners surveyed by Digit, chosen by over 56% of respondents, while cordless stick vacuums account for only 15% [citation:5]. This seems counterintuitive in a price-sensitive market—until you consider the value proposition. A robot vacuum cleans *without requiring the human to clean*. The automation justifies the premium.
Cordless stick vacuums don’t offer that autonomy. The human still pushes the device. So the justification has to come from elsewhere: superior cleaning power on Indian floors, wet-and-dry versatility, or a price low enough to make the experiment feel low-risk. The brands that succeed will pick one of these lanes and execute it without compromise. A ₹12,000 stick vacuum that tries to compete with a ₹25,000 Dyson on brand prestige is a wasted effort. A ₹6,500 stick vacuum that reliably picks up dust from a marble floor and has a service center within 30 kilometers is a category creator.
The Long Game
Forecasts for India’s cordless segment are optimistic. The cordless share of the wet-dry vacuum market is projected to overtake corded by 2032, reaching 35–40% of unit sales by 2035 [citation:4]. Deep Market Insights estimates the broader cordless vacuum market at $522.6 million in 2024, growing at a 6.43% CAGR through 2033 [citation:11]. Those numbers assume the category crosses the chasm from early adopters to the early majority—a transition that hinges entirely on trust.
Trust in India is built differently than in markets where vacuuming is already a habit. It’s built through demonstrations in local retail stores where a customer can see the suction pick up rice grains and fine atta from a tile sample. It’s built through warranty terms written in plain language, not legalistic fine print. It’s built through service technicians who actually answer the phone. And yes, it’s built through price points that don’t require a family committee meeting to approve.
The cordless vacuum brands that treat India as a discount bin for excess inventory will fail. The ones that treat it as a product-market fit problem—where price, performance, and service are designed together for a specific consumer who has never owned a vacuum before—have a rare window. The penetration number is 0.89%. The broom is still in the corner. That won’t last forever.
FAQ
Why is vacuum cleaner penetration so low in India?
A combination of cultural cleaning habits (the ubiquitous broom), historically high prices relative to perceived value, and a lack of trust in unfamiliar technology. Redseer data puts household penetration at just 0.89% [citation:9].
What price point is most promising for cordless stick vacuums in India?
Industry analysis points to the ₹5,000–8,000 range as the volume-unlocking tier, provided battery reliability and warranty support are not compromised [citation:4].
Do Indian consumers prefer robot vacuums over stick vacuums?
Survey data suggests robots are currently more common among owners (56% vs. 15% for cordless sticks), likely because automation justifies the premium more easily than a manual push device [citation:5].
How important is after-sales service for vacuum brands in India?
Critical. Over 17% of owners report dissatisfaction with after-sales, and neutral sentiment is widespread. In a low-penetration market, poor service generates word-of-mouth damage that suppresses the entire category [citation:5].
Are Chinese-made cordless vacuums suitable for Indian conditions?
The supply chain is capable, but product design must account for Indian floor types (hard tile, marble), fine dust, and the expectation of wet cleaning. Localized filtration and mopping functionality matter more than raw suction specs alone.